B2B invoicing and corporate mobility in Morocco: why you should formalise your Casa-Rabat intercity transfers under a framework contract with deductible VAT
Corporate mobility in Morocco often plays out along one short and very busy corridor. A director can move straight from a meeting at Casablanca Finance City to a steering committee at Technopolis and a team catch-up in Kénitra on the same day. Every journey eats into productive working time, and the repetition of round trips weighs as much on the diary as on the company’s transport budget. Teams that organise these journeys soon run into an administrative detail. A street taxi issues no usable document. An expense claim pieced together at the end of the month becomes fragile on the day of an inspection. The question of the supporting document therefore comes up before the question of the vehicle.
This guide describes how a corporate account works with a private transport operator serving Casablanca, Rabat and Kénitra. It is aimed at multi-site directors, procurement managers and office managers who want to move away from cash reimbursements and envelopes full of receipts.
To deduct VAT on a private transfer between Casablanca Finance City and Technopolis Rabat, the company must hold a compliant invoice issued by the operator, showing its ICE, its Identifiant Fiscal and its Registre de Commerce. The transport of passengers falls under the 14 % rate set out in the Code Général des Impôts (art. 89 and 99). The journey must serve the company’s business and be tied to a framework contract or a named purchase order. An online booking, with the company’s tax identifiers entered at the time of order, produces that supporting document at the end of the trip. On a disputed point, have the treatment settled by your accountant.
Why a framework contract changes the accounting treatment of journeys
An isolated journey is handled as a one-off purchase. Dozens of journeys a month handled one by one form a pile of documents that nobody really reconciles. The framework contract solves this volume problem by setting the rules of the game in advance between the operator and the client company. It turns a series of improvised orders into an identifiable expense line, with an annual budget and a named owner.
The document sets out who orders, for which sites, under which conditions, and how invoicing is issued. It designates a single point of contact on the operator’s side and an approval process on the client’s side. The finance department gains a stable framework for its entries. Employees gain a procedure with no personal outlay. This double effect explains why procurement departments often push for an annual commitment rather than separate orders.
Three points are negotiated at signature.
- The cancellation period that applies to rescheduled appointments.
- The frequency of invoices, issued individually or as a monthly summary.
- The granularity of the reporting supplied, by site, by employee or by project.
These clauses decide how flexible the arrangement really is.
What accounting expects before approving the expense
Four items come up in almost every request from accounts departments.
- An invoice made out to the company, never to the passenger.
- The date of the journey, the route and the identity of the passenger carried.
- The provider’s tax identifiers.
- A link to a purchase order, a contract or a cost centre.
A complete document passes inspection without comment. An incomplete one comes back with a request for regularisation, several weeks after the journey, at a point when nobody remembers the appointment concerned.
The check happens on receipt.
B2B invoicing and corporate mobility in Morocco: the mandatory details on a transport invoice
Moroccan regulations require the issuer of the invoice to show its full tax identity. A company that engages a private transport operator does not have to reconstruct these details. It does, however, have every interest in checking them before the first payment, and then at each change of provider. An invoice received without a check turns into an accounting dispute several months later, when the bank reconciliation throws up an inconsistent document. The useful reflex stays simple. The first invoice is read line by line, the following ones are checked on a sample basis.
ICE, Identifiant Fiscal and Registre de Commerce
Three identifiers structure the invoice. The ICE, or Identifiant Commun de l’Entreprise, links the issuer to the national register. The Identifiant Fiscal is used to track VAT and corporate tax. The Registre de Commerce number identifies the provider’s declared activity. A transport invoice that omits any one of the three weakens the whole file. The client’s accounts department sends it back for regularisation, and the expense waits before being booked. That delay feeds into the month-end close, and then into the VAT return. A check on receipt avoids this queue.
Linked to the client, not to the passenger
The passenger is not always the payer. An assistant travelling to a partner’s premises from Technopolis may travel on their employer’s account. The invoice then carries the company’s name, and the passenger’s name appears in the detail line. This distinction removes personal reimbursements and shaky paperwork. It also simplifies budget tracking, since each journey stays attached to an identifiable entity.
What makes an invoice open to challenge
An incomplete address, a wrong register number or a missing route is enough to create doubt. The heaviest case remains an invoice made out to an individual and paid from the company’s treasury. The link between the expense and the business then becomes hard to demonstrate.
What articles 89 and 99 of the CGI say about deductible VAT
The Code Général des Impôts governs the VAT applicable to passenger transport services. Articles 89 and 99 place these services at the 14 % rate. For a taxable company, the tax shown on the invoice opens a right to deduct, provided the expense serves the business and the invoice is in order. These two conditions are read together. A flawless invoice for a journey unrelated to the activity is still a non-deductible invoice.
The wording matters for a procurement department. Passenger transport is not treated like any other service. Its rate and its invoicing conditions follow an identified regime, distinct from the one applied to other categories of services. The choice of provider depends directly on it.
The 14 % rate and running a fleet
The tax applies to the service provided, invoiced by an operator that runs its own vehicles and employs its own drivers. An intermediary that resells a journey without a fleet falls under a different scheme. The nuance matters when choosing the provider to sign an annual contract with.
Meeting the conditions for the right to deduct
Three conditions come up in practice. The expense must be incurred in the interest of the business, the invoice must be made out to the company, and the payment must leave a bank trace. A cash payment handed to a driver meets none of these three conditions. A deduction disallowed produces two effects. The tax stays with the company, and the expense risks being added back to taxable profit. The real cost of the journey then far exceeds the amount shown on the initial quote.
Casablanca Finance City, Technopolis and Kénitra: three hubs, three constraints
The three hubs that shape the corridor do not produce the same working days. A useful mobility arrangement is set to these rhythms rather than to a single model.
Casablanca Finance City
Client meetings there are short and close together. A director strings together two or three encounters, then heads back to Rabat. The constraint lies less in the journey than in the waiting between two meetings, which a car with a driver absorbs better than a parking space to hunt for. It is also the natural starting point for hosting a partner on a day trip from Rabat to Casablanca with Hassan II Mosque ticket.
Technopolis Rabat
The site works in teams, with tight meeting slots. Round trips from Casablanca are often organised for several people, which argues for a minivan rather than a saloon car. The return at the end of the day remains the hardest part to cover.
Kénitra
Extending the corridor north lengthens the journeys. A trip from Kénitra to Rabat or Kénitra to Casablanca is prepared the day before, with a driver who knows the traffic windows on the motorway. Multi-site days then run through a private chauffeur service at your disposal, which is more flexible than a series of separately booked journeys.
The Casablanca-Rabat shuttle: booking a journey with corporate invoicing
Booking a shuttle between the two cities follows a short path, directly in the site’s booking engine. Specify corporate invoicing at the time of order, along with the route and the time you want.
Enter your company’s ICE and Identifiant Fiscal when you book. The supporting document then carries these details, with no re-entry and no correction request at the end of the month. The return leg is selected on the same screen, which sorts out late returns from Casablanca Finance City. An employee heading to Technopolis for a project meeting has nothing to pay upfront.
Book your return trip from the Booking Taxi Maroc booking form. Monthly volume to plan? Call +212 662 48 65 07 or write to Contact@bookingtaximaroc.com.
What happens after the journey
The invoice carries the operator’s tax details and the breakdown of the route. It is linked to the original order, and therefore to the declared cost centre. The accounts department has a complete document on the first pass.
Working during the journey: comfort, quiet and connectivity on board
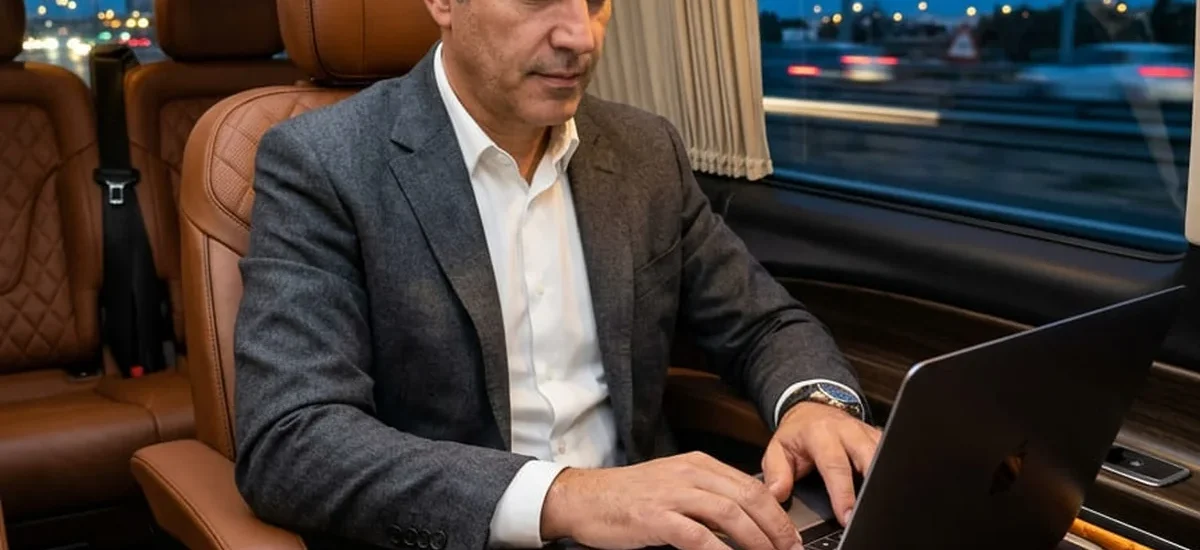
A journey spent in traffic is not worth the same depending on the vehicle. On board the Mercedes-Benz Vito and V-Class minivans, as well as the fleet’s executive saloons, the rear space turns into a mobile office. Continuous Wi-Fi connectivity makes it possible to hold a video call, deal with messages or finish a presentation before arrival. The quiet of the cabin counts as much as the connection. A client call made in a calm vehicle goes better than one in a crowded train carriage. For a director, this continuity of attention is the real counterpart to the time spent on the road, between the offices of Casablanca and those of Rabat.
The journey becomes a block of working time.
Building mobility reporting that the finance department can use
A corporate account is not only there to pay. It produces data. A monthly summary by site, by employee or by project turns the transport expense into a management indicator, usable in a management committee as well as in a budget review. Three uses come up with multi-site clients. Budget tracking compares actuals with forecasts by entity. Spend control spots journeys outside the authorised scope. The trade-off between a company car and chauffeured transport is settled on figures at last, never on impressions.
Grouped invoicing simplifies this work. One monthly document replaces dozens of scattered receipts, and the accounting reconciliation is done on a single item. The administrative load falls at close, without rising for the teams during the year.
The rest belongs to accounting.
Reporting follows invoicing.
Frequently asked questions about invoicing corporate transfers
How do I get an invoice in my company’s name for a Casablanca Finance City to Technopolis Rabat journey?
Enter your company’s ICE and Identifiant Fiscal when you book. The invoice is issued in the company’s name, with the details of the journey and the passenger. It carries the operator’s tax details and is linked to your order.
Can an employee travel on the company account?
Yes, as long as the journey serves the company’s business. The journey is invoiced in the employer’s name, and the passenger’s name appears in the detail line. No personal reimbursement is needed.
Which documents should be produced in the event of an inspection of transport costs?
The operator’s invoice, the purchase order or framework contract, then proof of bank payment. These three documents are enough to justify the expense and the tax that comes with it. Keep the breakdown of journeys as well when invoicing is monthly.
Is one invoice per journey needed, or a monthly invoice?
Both work. One invoice per journey suits occasional travel. The monthly summary suits regular shuttles between Casablanca, Rabat and Kénitra.
Can a chauffeur service at your disposal be part of a framework contract?
The service fits into the same invoicing arrangement, with the same mandatory details. It suits days with multiple appointments, where waiting times make the classic shuttle less suitable.
Booking a corporate journey on the Casablanca-Rabat corridor
The catalogue of journeys and excursions covers private transfers on the Rabat – Casablanca – Kénitra corridor, as well as full-day services with a driver at your disposal. For a business trip, choose the return shuttle, tick the corporate invoicing option and enter your company’s tax identifiers. For a monthly volume, several vehicles or a multi-site framework contract, the request goes through the same Booking Taxi Maroc booking engine, followed up with a call to +212 662 48 65 07 or an email to Contact@bookingtaximaroc.com.
The tax points mentioned in this guide (Code Général des Impôts, articles 89 and 99, 14 % rate, ICE, Identifiant Fiscal and Registre de Commerce details) call for a check against your own situation. Have your accountant confirm how your invoices are treated before launching a campaign of deductions.
Sources: CGEM, Confédération Générale des Entreprises du Maroc and Office National Marocain du Tourisme (ONMT).